Donation

Donation
Donation amount as little as $10. Please donate generously. To donate, click on the sggives logo.

Blog Archive

Showing posts with label New Toyo. Show all posts

Sunday, 3 March 2013

SRS - Closing Status 1 Mar

Sold away my holding in New Toyo 2 lots in this week under SRS portfolio at break even (minimal loss of -$1).  It reported lower revenue and profit comparing to last year for quarter 4.  l will look at New Toyo performance at half time in 2013 to see if it is worth investing in this company going forward.

In this week l have also added GRP 21 lots for my SRS portfolio.  At half time, revenue was flat +1.0% and profit +17.1%.  GRP declared an interim dividend of $0.05 ($0.01 + special $0.04).  Its XD date in not known yet.  And if it maintain final dividend at $0.01 then dividend yield will be 17.6% based on my investment cost in it.

Also for my SRS portfolio l have invested into GLP (Global Logistic Properties) 5 lots in this week.  Government of Singapore Investment Corp. (GIC) recently reduced its stake in GLP to 37% from 49%.  This is part of GIC rebalancing of its holdings so l reckon there is really nothing fundamentally wrong with GLP.


Portfolio walk since previous posting :-

+$5,527 Total Returns as of 22 Feb

-$1 Loss on sales of New Toyo

-$215 Unrealised positions worsened

+$5,311 Total Returns as of 1 Mar

previous posting :- SRS - Closing status 22 Feb
Saturday, 10 November 2012

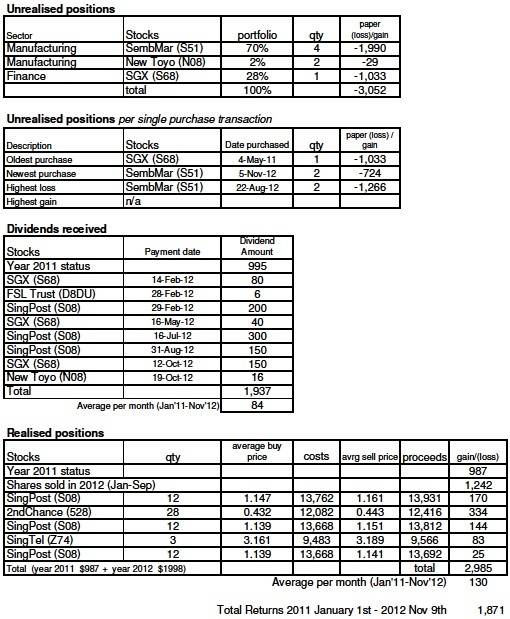
SRS - Closing Status 9 Nov

Received SRS statement from the bank this week and it shows dividends received from both New Toyo and SGX.

In this week under SRS portfolio l have added Sembcorp Marine 2 lots, before its 3rd quarter results announcement. I have thought that it would have completed certain work-in-progress projects in hands and hence reporting its revenue in 3rd quarter results. Well, this was held back and so it reported quite a low revenue for the quarter; in fact it was the lowest versus past two quarters on sequential basis. l have now over invested on Sembcorp Marine so l will not accumulate on further weakness of its share price; even knowing that it will definitely report a very high revenue in the final quarter.


Portfolio walk since previous posting :-

+$3,097 Total Returns as of 2 Nov

+166 Dividends from New Toyo and SGX

-$1,392 Unrealised positions worsened

+$1,871 Total Returns as of 9 Nov

previous posting :- SRS - Closing status 2 Nov

Sunday, 2 September 2012

SRS - Closing Status 31 Aug

In this week under SRS portfolio, I have managed to sell New Toyo 18 lots of the 20 lots which l have queued.   Based on the declared dividend rate, l have set its exit selling price for a gain of around $144 (18 lots x $0.0080); and the gain of $123 is close enough.  Will re-invest into New Toyo when its share price weakens again.

Also in this week, l have invested into Hutchison Port Hldg Trust (SGD) 8 lots this week.  I am hoping to accumulate HPH Trust at lower prices.  With its annual dividend yield above 8% so even when the stock market sink and l am stuck with this investment for a long period of time, it's really worth going long with it. But  then l will still plan and execute my exit selling price accordingly.


Portfolio walk since previous posting :-

+$1,459 Total Returns as of 24 Aug

+$123 Gain on sales of New Toyo

+$189 Unrealised positions improved

+$1,771 Total Returns as of 31 Aug

previous posting :- SRS - Closing status 24 Aug

Saturday, 25 August 2012

SRS - Closing Status 24 Aug


New Toyo declared a lower dividend payout of $0.80 versus previous year's $0.97.  This is probably the reason for its share price softness recently.  I have already received my first round of advance dividend of $60 (actual would be 8 lots x $0.80 = $64) and now hoping to get a second round of it when l have re-invested into New Toyo 20 lots this week under SRS portfolio. But this time round it is probably slightly lower at around $140 ---> expected advance dividend to 'receive' 20 lots x $0.80 = $160 versus (1) selling at $0.285, gain of $140 or (2) selling at $0.29, gain of $240.  Even if l am stuck with this investment, l continue to believe New Toyo management is able to bring more business and profit despite its divestment of profitable associate company Shanghai Asia Holdings.  New Toyo also sold off its loss making Pakistan subsidiary.  Future revenue would be affected due to plain packaging guidelines in Australia starting from Dec'12 but unlikely to cause huge impact on its profit because of corresponding cost of production reduction.  New Toyo is definitely not resting on its laurels as it is actively seeking Infinite Possibilities.  

I have also invested into Valuetronics 25 lots this week under SRS portfolio. Its share price gone into after XD on 23 July.  In its 1Q13 results, revenue was higher 20% yoy but at lower profit margin because of product mix.  Inventories, Receivables, Bank balances and Trade Payables are also higher but l reckon these are due to effect of higher revenue in 1Q13. Valuetronics ceased its loss making Licensing business and will be recording its termination expenditure in next quarter (2Q13).  I think this is an important development as it continues to be forward looking and not hesitate on Adaptability to a changing marketplace.


Portfolio walk since previous posting :-

+$1,428 Total Returns as of 10 Aug

+$31 Unrealised positions improved

+$1,459 Total Returns as of 24 Aug

previous posting :- SRS - Closing status 10 Aug

Saturday, 7 July 2012

Cash - Closing Status 6 Jul

New Toyo
Managed to clear off the remaining New Toyo 4 lots under Cash portfolio this week.  As mentioned in previous posting that l am expecting the rejuvenated new management team able to bring in more revenue and profit to the company which will further solidify its cash flow (and balance sheet).  Looking at investing into New Toyo when it price is attractive again.

HTL International
Invested into HTL 3 lots in mid April.  1st quarter results which was released in May was rather disappointing and scary.  Yes, its revenue catapulted 24.2% in 1st quarter but dangers which lurk in every aspects of its businesses are indeed a very serious concern :-

1.Its biggest sales at 49% is in Europe and everyone are well aware that this region is in chaotic condition now and there are many other important priorities in life than owning a luxury sofa.

2.Sofa business is at 94% of its core businesses and it is facing rising material and production costs.  GP margin from dropped from 35.3% to 33.4%. These cost pressures have outpaced  product selling price adjustments to customers.

3.Net borrowings increased by 31% or US$16.4 million due to more working capital required to fund higher production to meet increased in sales demand.

4.Negative FCF of US$15.7m in Q1 2012 as compared to a positive US$4.0 million in Q1 2011.

With the above bad news and other negatives, l reckon HTL will face extreme difficult times ahead.  l have been in the sell queue for almost 1.5 months and have finally managed to divest the entire 3 lots at par (minimal gain $5) this week. 


Portfolio walk since previous posting :-

-$496 Total Returns as of 29 Jun 

+$46 Profits on sales of HTL and New Toyo

-$119 Unrealised positions worsened

-$569 Total Returns as of 6 Jul

 previous posting :- Cash - Closing Status 29 Jun 

Saturday, 30 June 2012

Cash - Closing Status 29 Jun

For the Cash portfolio this week, l have received a cheque in the mail on the dividends for Foreland Fabrictech.  I am hoping for Foreland to improve on its share price and giving out higher dividends in the near future.  Otherwise, l will need to find a way to reduce and eventually divest my investment in it.

Based on previous year, the next XD dividend date on ST Engineering is on 8 Aug at the rate of $0.03 and for my 3 lots investment in it then the projected dividends receivable is at $90.  This week l have sold it all away so that l can receive its dividends in advance in the form of a disposal gain of  $147.

Bought into New Toyo 8 lots this week but l have halved my investment in it within this week itself.   The original plan was to divest the entire 8 lots because current price is already meeting my selling price target for an advance dividends.  But unfortunately only managed to sell off 4 lots; which actually lowered the expected gain on the disposal because of inability to apportion out the brokerage  charges on reduced number of shares sold.  For next week, l will continue to divest the remaining 4 lots as l doubt current stock market bull run is sustainable and l am hoping to re-invest into it again at lower prices in the near future.  l am attracted to New Toyo as it has gone through several management and operations makeovers in recent and past months.  l reckon that all these makeovers at New Toyo were and are necessary in order for it constantly improving its operations efficiency and lowering running costs in the long run.  


Portfolio walk since previous posting :-

-$605 Total Returns as of 15 Jun 

+$252 Dividends received from Foreland

+$167 Profits on sales of ST Engineering and New Toyo

-$310 Unrealised positions worsened

-$496 Total Returns as of 29 Jun

 previous posting :- Cash - Closing Status 15 Jun 

BrainyQuote

The Motley Fool

NextInsight

PropertyGuru

SGX News

Hellenic Shipping News

Singapore Law

Business Google News

Business Times