Donation

Donation
Donation amount as little as $10. Please donate generously. To donate, click on the sggives logo.

Blog Archive

Showing posts with label SGX. Show all posts

Tuesday, 9 February 2016

Saturday, 7 November 2015

Saturday, 19 September 2015

Sunday, 12 May 2013

Cash - Closing Status 10 May

I have increased my holding of Telechoice 2 lots for my Cash portfolio this week so l have 4 lots of it now. 

In my posting on 26 April l have indicated my intent to sell off SGX 1 lot at break even and this was achieved in this week.  Hope to re-invest into SGX at lower share price level.

Also in this week l have decided to divest my positions in the following :-

UMS
No. of shares : 5 lots; Date of investment : 3-May-13; Nett profit : $13
Remarks :- Divestment was after its XD date so l will be paid on its dividend of $100 (5 lots x dividend rate $0.02) on 29 May.   To re-invest into UMS at lower share price level.

CDW
No. of shares : 11 lots; Date of investment : 1-Mar-13; Nett profit : $47
Remarks : Halved CDW holding in order to lock-in profit.  Nett profit was 50% lesser than the expected dividend which will go XD on 20 May.  Nobody can predict where is the share market heading to so it is better to get back some returns whereby the nett profit of 2.9% (over investment costs) is already better than bank deposit rate.

2nd Chance
No.of shares : 23 lots; Date of investment : 3-Apr-13; Nett profit : $180
Remarks : Announced in this week that Director bought its shares in open market.  I took this opportunity to offload my entire holding in 2nd Chance.  Based on my investment costs in it, nett profit is at 1.9%  which is better than bank deposit rate.

K1 Ventures
No. of shares : 5 lots; Date of investment : 3-May-13; Nett profit : $21
Remarks : Investment costs for 5 lots is less than $1k.  And nett profit is at 2.6% which better than bank deposit rate.


Portfolio walk since previous posting :-

+$1,651 Total Returns as of 3 May

+$261 Gain on sales of SGX, UMS, CDW, 2nd Chance, K1 Venture

+$544 Unrealised positions improved

+$2,457 Total Returns as of 10 May

Previous posting :-  Cash - Closing Status 3 May

Sunday, 28 April 2013

Cash - Closing Status 26 Apr

I have re-invested into SGX twice this week at 1 lot each time under Cash portfolio.  In the same week l have decided to reduce my holding in it to 1 lot.  The 1 lot which l have divested was at a nett gain of $32 which is around 79% of its recent dividend which went XD this week and payment will happen on 2 May.  So l have collected total of $63 dividends (nett gain last week $31 + current week $32) in advance.  For the remaining l lot holding in it l am hoping to be able to divesting it away at break even.   Not that l have given up on SGX but l am hoping to re-invest into it at a lower share price level.  SGX will always be my radar as a favorite stock to invest in.   

l have divested SPH 1 lot this week from my Cash portfolio at nett gain of $68.  This is as good as collecting its $70 (1 lot x dividend rate $0.07) dividend in advance; it is going XD on 7 May and its scheduled payment is on 23 May.

Managed to get into Duty Free 3 lots this week at lower price level after having divested it away the previous week at break even.  4Q2013 results was an "interesting" one.  Gross profit margin was unchanged at 29.9% comparing to 4Q2012 (at 30.0%) but its comment on its performance by account line somehow clouded its true operation efficiency and profitability.   Higher revenue was said due to combination of higher selling price and higher volume in its Duty Free business segment (which is 97% of total business); so why GP% was flat? Change in inventories is positive amount so it is a "gain" item and it explained it as due to timing difference in purchases and consumption of inventories as closing inventories as of 4Q2013 was much higher.  I reckon it is more appropriate to explain the change (in value) of inventories on the aspects of forex and stock valuation basis and not on the vague and general basis of timing.  Inventories purchased and material consumed was much higher due to overall increase in purchase volume in order to enjoy better purchasing terms from suppliers - l am totally lost here as wouldn't it be better explained that it was in line with higher revenue?  By better purchasing terms l guess this means better credit payment term as in the balance sheet it explained higher inventories due to increase in purchase quantity coupled with increase in cost of purchases.  No details given on Donations of $3mil.   My investment costs in Duty Free for 3 lots was for a small amount at $1.2k and will always be at this costs level in order to contain any potential investment risk in it.  

  
Portfolio walk since previous posting :-

+$1,693 Total Returns as of 19 Apr

+$100 Gain on sales of SGX and SPH

+$149 Unrealised positions improved

+$1,942 Total Returns as of 26 Apr

Previous posting :-  Cash - Closing Status 19 Apr

Sunday, 21 April 2013

Cash - Closing Status 19 Apr

This week for my Cash portfolio l have decided to divest Duty Free 3 lots at break even.  I have not changed my view of its investment worthiness but it's just because l am trying to re-enter into it at slightly lower price level.

l have pared down on my holding in UMS by 45 lots this week.  Decided to do so because l was thinking of re-investing into it at lower price level.  Seems that l have got wrong as its share price moved higher instead; possibly due to its CD status at the moment.

Invested into SPH 1 lot this week under Cash portfolio.  Its share price crashed from its recent 52 weeks high of $4.68 (on 11 Apr) to lowest price level of $4.22 (on 17 Apr) this week due to its poor
Qtr 2 results - Revenue -6% and Profit -15%.   l certainly think it is a knee jerk reaction and present a good opportunity to get into SPH on a pullback on its share price.

Also this week l have invested into SGX 1 lot.  It posted double results for Qtr 3 - Revenue +17%, Profit +26%.  The various initiatives and collaborations happened in Qtr 3 alone are attestation of SGX's vigor to place itself in a higher level of playing field and hence pulling itself ahead of other world's exchanges.  Forget about Manchester United failed IPO listing here as there are many more big names coming our way with SGX relentless efforts and emphasize of more rigor with compliance of certain rules and regulations of its listed companies.  There is possibility of Formula One going for IPO here.  There is great revenue to come in SGX's way so it's a great company to invest in.  It is going XD on 22 April so time being l have divested my holding in it in the same week for a nett gain of $31; which is 76% of the total dividend amount payable on 2 May but l have already collected it in advance now.  Will re-invest into SGX at lower price level.


Portfolio walk since previous posting :-

+$2,000 Total Returns as of 12 Apr

+$115 Gain on sales of Duty Free, UMS and SGX

-$422 Unrealised positions worsened

+$1,693 Total Returns as of 19 Apr

Previous posting :-  Cash - Closing Status 12 Apr

Sunday, 10 March 2013

SRS - Closing Status 8 Mar

Received SRS statement for Feb'13 month from the bank this week and it showed $40 dividends received from SGX.

I have divested my stock holding in GLP (Global Logistics Properties) 5 lots this week from my SRS portfolio for a gain of $110. 


Portfolio walk since previous posting :-

+$5,311 Total Returns as of 1 Mar

+$40 Dividends collected from SGX

+$110 Gain on sales of GLP

+$115 Unrealised positions improved

+$5,577 Total Returns as of 8 Mar

previous posting :- SRS - Closing status 1 Mar

Sunday, 3 March 2013

Cash - Closing Status 1 Mar

In this week for my Cash portfolio l have made several investments and divestments, as listed below :-
 
Assuming that SGX's next dividends rate is at $0.04 for XD around 30 April then based on my 1 lot holding in it then the expected dividend amount is $40.  In this week l have sold it away for a profit of $61 so it is as good as l have collected its dividends in advance.  

Invested into GLP (Global Logistic Properties) 1 lot but as it is a growth stock so l have eyed an exit selling price for a returns which is better than bank deposit interest rate.  I have sold it away within the same week for a profit of $36 (1.3% yield).  On the next day, Government of Singapore Investment Corp. (GIC) reduced its stake in GLP to 37% from 49%.  This is part of GIC rebalancing of its holdings so l reckon there is really nothing fundamentally wrong with GLP. 

CDW reported a strong set of results this week to end full year on Revenue +13.5% and Profit +143.1%.  In this week l have invested in CDW 22 lots.  A higher final dividend rate of $0.007 has been declared which is likely to XD on 3 May (tentative announcement on 3 Apr).  If l am stuck with it in a bear market then based on my investment cost in it and historical total dividend in past calendar years (2006-2012), l am expect a range of dividend of around 2% - 6%.  I am attracted to its current dividend of $0.007  but l must remember that CDW is likely to turn in lower revenue and profit in FY 2013 so l do not wish to holding on to it for a longer period of time.  I do hope to be able to divest it all away soon.

Singapore Shipping Corp (Sp Ship) announced a set of soft results for Qtr 3 on 4 Feb. but its share price was not badly affected by it. As of 9M2013 its revenue was flat at +2% and profit +42.3% (because of successful insurance claim).  l will not expect Sp Ship to report a profitable Qtr 4 looking at the costs and expenses which are escalating. At full time, l do expect revenue to continue staying at flat growth rate; and profit to stay almost the same growth rate as in 9M2013.  For this week l have invested into Sp Ship 10 lots.  It pays dividends only once in a year and have been quite stable at $0.01 which is 4.24% yield based on my invested costs in it.

Added GRP 10 lots in this week. At half time, revenue was flat +1.0% and profit +17.1%.  GRP declared an interim dividend of $0.05 ($0.01 + special $0.04).  Its XD date in not known yet.  And if it maintain final dividend at $0.01 then dividend yield will be 17.6% based on my investment cost in it.

Also in this week l have bought into Duty Free International 2 lots. Atlan Holding is Duty Free shareholder at 81%.  Malaysian billionaire, Vincent Tan has deemed interest in Duty Free via his holding in Berjaya Group which is controlling 25% of Atlan Holding.  Its 9M2013 results have been good though could have been better if not for the increases in certain expenses categories.  Using 3Q2012 running rate Duty Free should be able to hold its financials growth rates in 9M2013 at full time.


Portfolio walk since previous posting :-

+$1,913 Total Returns as of 22 Feb

+$97 Gain on sales of SGX and GLP

-$986 Unrealised positions worsened

+$1,024 Total Returns as of 1 Mar

previous posting :-  Cash - Closing Status 22 Feb

Saturday, 23 February 2013

Cash - Closing Status 22 Feb

Invested into GRP 2 lots and Sin Ghee Huat 2 lots under Cash portfolio this week.  The invested amounts were small as l was toying with the idea of investing into many stock counters to spread out risks and returns.  But in the end fear got the better of me because of markets struggling with resistance levels a few times so l have sold them all away in the same week. Another investing lesson for me here to remember whereby if and when l am able to have better control over it then l can actually leverage from it for a stable or higher yield.     

GRP posted an unexciting but fairly stable results at half time.  The only exciting element is the proposed $0.05 ($0.01 + special $0.04) total interim dividends.  This is because in each calendar year, GRP is paying an annual dividends of $0.02.  At half time, revenue and gross profit margin were almost flat vs the previous year.  There is no update on its 12.7% shareholding in Aphrodite Gold company but a quick visit to ASX is showing positive news in it.  Operating cashflow for GRP at half time is positive but lower vs last year.  There is no borrowings.  Will re-invest into GRP when its share price weakens.

Sin Ghee Huat posted an unexciting and slightly weaker results at half time.  It pays dividends only once in a year, in Nov month and it is quite stable at around $0.02 and at current price of $0.28 then this represents a 7.1% annual dividend yield.  At half time, revenue and gross profit margin were lower vs the previous year. This is due to lower margin from "project orders" in quarter 1; but in quarter 2 gross profit margin is back to normal at around 23%,  Operating cashflow for Sin Ghee Huat at half time is positive and higher vs last year.  There is no borrowings.  Will re-invest into Sin Ghee Huat when its share price weakens.


I have added SGX 1 lot into my Cash portfolio this week.  Its half time results were unexciting but this is a blue chip company so there is no worry of collapse even when the markets conditions suddenly turn topsy turvy.  It offer a genereous and stable dividend income stream.


Portrtfolio walk since previous posting :-

+$2,286 Total Returns as of 15 Feb

+$14 Gain on sales of GRP and Sin Ghee Huat

-$387 Unrealised positions worsened

+$1,913 Total Returns as of 22 Feb

previous posting :-  Cash - Closing Status 15 Feb


Saturday, 2 February 2013

SRS - Closing Status 1 Feb

For my SRS portfolio this week, l have sold away City Developments 2 lots for a nett gain of $163.  This nett profit could have been much higher (around 4-5 times more) if l have sold it off in 1-2 days later.  l am not cut into investing in growth stock yet as l realized that l have not mastered the art of being more patient.

My oldest stock holding under SRS portfolio is SGX 1 lot, which l have invested into it in May'11.  Annual dividend yield is around 3.5% so it is a pretty good stock to own.  As the stock is already in profit position so l have decided to sell it away for a nett gain of $38.  Will re-invest into it again when its share price weakens.

When l invested into Sing Investments 7 lots two weeks ago l have actually wanted to keep it for its annual dividend yield of around 5%.  But this week l have sold it all away for a nett gain of $71 because l reckon l have tied up a huge sum of funds into a company which pays dividends only once in each year.  Ideally l would prefer such big amount of investment to be put to work in a much harder cycle of investments and re-investments for a higher returns.  I will re-invest into Sing Inv but this will be limited to 1-2 lots as passive income.


Portfolio walk since previous posting :-

+$5,196 Total Returns as of 25 Jan

+$272 Gain on sales of City Developments, SGX and Sing Investments

+$52 Unrealised positions improved

+$5,519 Total Returns as of 1 Feb

previous postings :- 
SRS - Closing status 25 Jan
City Developments, donations, blah blah

Sunday, 9 December 2012

SRS - Closing Status 7 Dec

Received SRS statement from the bank this week showing dividends received from SGX for $40 in Nov'12.

There have many news about illegal fishing by Pac Andes and its related company in Russian water in recent weeks.  And this has cause its share price been sold off to its 52 weeks low now and l think it is really in badly oversold position.  I reckon that it is normal to face political hurdles in doing businesses in foreign countries and Pac Andes will be able smooth sailing out of this tormenting storm soon.  This week l have invested into  Pac Andes 25 lots under SRS portfolio.

Also this week l have invested into Mapletree Logistics 5 lots under SRS portfolio.  I am not sure what are the impact of its failed divestment of its Woodlands property, the acquisition plan of Wuxi Logistics Park, and the recent 1.15mil new units issued for those participated in the distribution reinvestment plan.  But l do hope it can maintain its full year dividends of $0.0681 so that based on my investment costs in it l will get an annual dividend yield of 6.2%.  But l am likely to sell it away if l can already get one quarter of its dividends in advance.

I have sold off GRP 15 lots in this week under SRS portfolio for a gain of $167.  And l have missed its astronomical volume on Friday and its share price had escalated since then; such is the unpredictable action and direction of share market.  Even though the gain amount was smaller at $167 than if l have sold it off at higher share price on Friday but it was slightly higher than $150 which was the exit selling price target l have set (dividend rate of $0.01 x 15 lots).  In a way, l have been paid in advance on dividends which would XD in Mar'13.


Portfolio walk since previous posting :-

+$3,018 Total Returns as of 30 Nov

+$167 Gains on sales of GRP

+$40 Dividends from SGX

-$234 Unrealised positions worsened

+$2,991 Total Returns as of 7 Dec

previous posting :- SRS - Closing status 30 Nov

Saturday, 10 November 2012

SRS - Closing Status 9 Nov

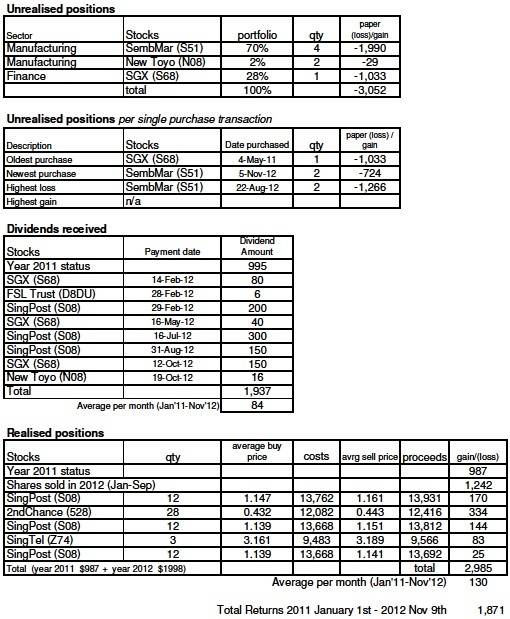
Received SRS statement from the bank this week and it shows dividends received from both New Toyo and SGX.

In this week under SRS portfolio l have added Sembcorp Marine 2 lots, before its 3rd quarter results announcement. I have thought that it would have completed certain work-in-progress projects in hands and hence reporting its revenue in 3rd quarter results. Well, this was held back and so it reported quite a low revenue for the quarter; in fact it was the lowest versus past two quarters on sequential basis. l have now over invested on Sembcorp Marine so l will not accumulate on further weakness of its share price; even knowing that it will definitely report a very high revenue in the final quarter.


Portfolio walk since previous posting :-

+$3,097 Total Returns as of 2 Nov

+166 Dividends from New Toyo and SGX

-$1,392 Unrealised positions worsened

+$1,871 Total Returns as of 9 Nov

previous posting :- SRS - Closing status 2 Nov

Tuesday, 18 September 2012

SRS - Closing Status 14 Sep

Updated as of 18 Sept
Updating this post on SGX.  I am full of surprise with SGX share price strength as it closed the day at $7.19.  It is probably due to its current CD status.  Should l have hold on to SGX and waited till closer to 26 Sept when it goes XD?  This is another lesson learnt but am uncertain of a fail-proof answer to this - how to know the real strength of a company which will XD in one to two weeks time? 

As written 16 Sept
I was attracted with SGX due to its price weakness recently so, l bought 2 lots of it this week under SRS portfolio.  I have an existing 1 lot of it currently running at loss of $690.  With a total of 3 lots, target selling price to break-even is at $7.19 and l am not sure whether this is achievable.  Its share price may have weaken but l reckon l have invested into it at quite a high price level so, I have decided to sell away 2 lots in the same week itself for a gain of $83.

Divested Valuetronics 25 lots this week for a gain of $116.  Will re-invest into it again when its share price weakens to an attractive level say, below 19 cents.


Portfolio walk since previous posting :-

+$2,001 Total Returns as of 7 Sep

+$199 Gains from sales of SGX and Valuetronics

+$89 Unrealised positions improved

+$2,289 Total Returns as of 14 Sep

previous posting :- SRS - Closing status 7 Sep

Saturday, 9 June 2012

SRS - Closing Status 8 Jun

Received the SRS statement for May month in the mail this week.  There was a dividend received for  SGX of $40.

For this week, l have re-invested into M1 for 5 lots.   Its next dividend XD is some time in July and if l want to get paid on its dividend earlier then l will need to sell it at $2.50.  But as the market is still so uncertain then l can only get paid in advance on the dividends when l repeat the selling  and re-investments cycle.

Portfolio walk since previous posting :-

-$946 Total Returns as of 11 May 
 
+$40 Dividends from SGX

-$850 Unrealised positions worsened

-$1,756 Total Returns as of 8 Jun

previous posting :- SRS - Closing status 11 May

Saturday, 10 March 2012

SRS - Closing Status 9 Mar


The only movement under the SRS category is the dividends received.  From the bank statement received this week, dividends received in the month of February were from SGX, FSL Trust and SingPost.


Portfolio walk since previous posting :-

-$1,780 Total Returns as of 17 Feb 

+$286 Dividends on SingPost, SGX and FSL Trust

+$105 Unrealised positions improved

-$1,389 Total Returns as of 9 Mar


previous journal :- SRS - Closing Status 17 Feb

BrainyQuote

The Motley Fool

NextInsight

PropertyGuru

SGX News

Hellenic Shipping News

Singapore Law

Business Google News

Business Times